Borrowing money is often viewed negatively, but when used responsibly, it can be a valuable financial tool. Whether you want to cover an unexpected expense, invest in your education, start a business, or achieve another major financial goal, responsible borrowing can provide access to funds when you need them most.
The key is understanding how loans work, choosing the right borrowing option, and making sure you can comfortably repay what you owe.
What Is Responsible Borrowing?
Responsible borrowing means taking on debt only when necessary and only when you have a realistic plan to repay it. It involves understanding the total cost of a loan, comparing available options, making payments on time, and avoiding debt that could place unnecessary pressure on your finances.
Before borrowing, consider your income, existing financial commitments, interest rate, repayment period, fees, and the purpose of the loan.
How Borrowing Can Support Your Financial Goals
1. It Can Help You Handle Unexpected Expenses
Unexpected expenses can disrupt even a carefully planned budget. Medical bills, urgent repairs, school expenses, or other emergencies may require more money than you currently have available.
A suitable loan can provide temporary financial support, allowing you to address the expense while spreading repayment over an agreed period.
However, borrowing for emergencies should be approached carefully. If possible, building an emergency fund can reduce your dependence on credit over time.
2. It Can Help You Invest in Education
Education and professional training can improve your skills and potentially create new career opportunities. For some people, borrowing can make it possible to pay for tuition, professional certifications, equipment, or other education-related costs.
Before taking an education loan, consider the expected benefits and whether the future cost of repayment fits your financial plans.
3. It Can Support Business Growth
Entrepreneurs and small-business owners may sometimes need additional capital to purchase equipment, increase inventory, expand operations, or manage cash flow.
Responsible business borrowing can help a company pursue growth opportunities without requiring the owner to fund everything from personal savings.
The important consideration is whether the business can generate enough cash flow to comfortably meet the loan repayments.
4. It Can Help You Make Planned Purchases
Certain major purchases may be difficult to pay for entirely from savings. Depending on the circumstances, financing can make it possible to spread the cost over time.
Before borrowing, compare the total amount you will repay with the cash price of the item. A lower monthly payment does not necessarily mean a cheaper loan because a longer repayment period can increase the overall interest paid.
Key Rules for Borrowing Responsibly
Borrow Only What You Need
One of the simplest ways to manage debt is to avoid borrowing more than necessary. A larger loan may provide extra cash today, but it also means higher repayments and potentially more interest over time.
Calculate the amount you actually need and avoid using additional credit simply because it is available.
Understand the Total Cost of the Loan
Don’t focus only on the monthly repayment. Before signing a loan agreement, check the interest rate, fees, charges, repayment schedule, and total amount payable.
Understanding the full cost allows you to compare different borrowing options more effectively.
Make Payments on Time
Late or missed payments can lead to additional charges and may negatively affect your credit history, depending on the applicable credit-reporting system.
Setting reminders or arranging automatic payments can help you stay on track.
Keep Your Debt Manageable
Your loan repayment should fit comfortably within your regular budget. Consider your existing debts and other financial obligations before taking on additional borrowing.
A loan that looks affordable on paper may become difficult to manage if your income changes or unexpected expenses arise.
Compare Loan Options
Don’t automatically accept the first loan offer you receive. Compare interest rates, fees, repayment periods, eligibility requirements, and other terms from reputable lenders.
Taking time to compare options can help you find financing that better matches your financial circumstances.
Borrowing vs. Saving: Which Should You Choose?
The right choice depends on your situation.
If an expense is not urgent, saving beforehand may allow you to avoid interest and borrowing costs. For an immediate need or an opportunity that could reasonably improve your financial position, borrowing may sometimes be appropriate.
A useful question to ask is:
“Will this borrowing help me achieve an important financial goal, or am I simply spending money I don’t currently have?”
That distinction can help you make more deliberate financial decisions.
Create a Repayment Plan Before You Borrow
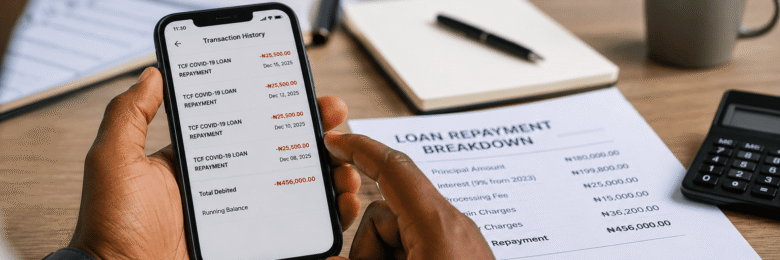
Before taking out a loan, create a simple repayment plan. Start by calculating your expected monthly payment and reviewing your monthly income and expenses.
For example, if your loan repayment is ₦50,000 per month, make sure your budget can accommodate that payment alongside rent, food, transportation, utilities, savings, and other existing commitments.
It is also wise to consider what would happen if your income temporarily decreased or an unexpected expense occurred.
Avoid Using Debt to Fund Unnecessary Spending
Responsible borrowing is fundamentally about purpose and affordability. Using loans repeatedly for non-essential purchases can create a cycle of debt that becomes increasingly difficult to manage.
Credit can be useful, but it should not replace a sustainable budget or regular savings habit.
Build a Stronger Financial Future
Borrowing can be one component of a broader financial strategy. Used carefully, it may help you manage emergencies, invest in education, support a business, or achieve other meaningful goals.
The goal should not simply be to access more credit. Instead, focus on borrowing within your means, understanding the terms, maintaining timely repayments, and gradually building savings and financial resilience.
Final Thoughts
Responsible borrowing can help you reach important financial goals when it is approached with careful planning. The most important steps are to borrow only what you can afford to repay, understand the total cost of the loan, compare your options, and maintain a realistic repayment plan.
Debt itself is not automatically good or bad. What matters is how much you borrow, why you borrow, the terms you accept, and how effectively you manage repayment.
With thoughtful financial planning, borrowing can become a tool rather than a burden—and can support your progress toward greater financial stability and long-term goals.
